0
EUR/USD traded in a narrow range during Asian trading on Thursday (Oct 29), changing hands around 1.1150, just above the low hit on Oct 14.
The European Central Bank was set to keep its deposit rate unchanged at 2.50% this week. Inflationary pressures have persisted since the rate hike in September. Oil and gas prices have risen sharply and are now well above the assumptions used in the ECB’s adverse scenario, with the headline HICP inflation rate projected to rise above 4% in the coming months.
Meanwhile, a steep rise in sovereign bond yields and tighter overall financial conditions have tempered policymakers’ urgency to raise rates.
This shift followed remarks made by Christine Lagarde to the European Parliament last month, where she acknowledged that a sharp increase in long-term rates would weigh on growth and reduce policy transmission.
Market pricing for an October rate hike was subsequently removed, and rates were expected to stay on hold this week.
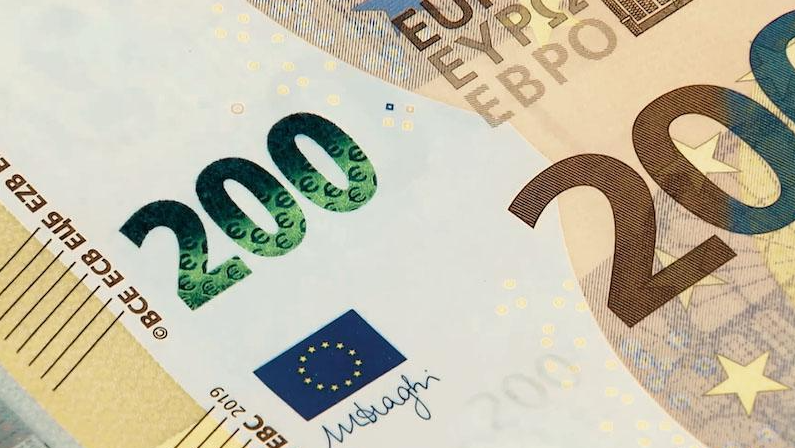
Second-round inflation effects and mixed domestic data
Domestic data on second-round inflation effects have remained generally moderate. The price components of the latest PMI survey showed a sharp acceleration in manufacturing input costs, yet this has not translated into broad gains in selling prices; services output prices even edged lower in October. ECB consumer surveys showed households’ medium- and long-term inflation expectations were stable, while the one-year gauge ticked up to 3.1%.
The latest SAFE survey for Q3 showed firms reporting higher expectations for inflation, wages and selling prices. The ECB flagged a substantial change in the survey sample composition, with a large share of responses coming from first-time respondents. Once this factor is accounted for, the figures do not provide convincing evidence that material second-round inflation risks have emerged.
Growth signals have been mixed. An ECB blog post highlighted the ongoing narrative of economic resilience despite tighter financial conditions and higher energy prices. The flash October PMI softened, led by France, although French readings merely retraced to August levels without sending more alarming signals.
Outside France, German manufacturing PMI showed constructive signs. The latest Ifo survey from Germany reaffirmed the broader resilience story, with the expectations component improving for the sixth consecutive month.
December emerges as a key policy window, with reduced conviction
The Governing Council faces a more complicated set of signals compared with a month earlier, making a pause at this meeting reasonable. December stands out as a natural window for another rate adjustment, when updated projections will be available. Unless energy prices reverse sharply before then, inflation forecasts will look less favourable than in September. Current oil and gas prices are already above the ECB’s adverse scenario assumptions.
Expectations for further tightening have cooled amid tighter financial conditions and limited survey evidence for strong second-round effects. Worsening bond market conditions could narrow the scope for additional pre-emptive policy action.
Press conference in focus: Lagarde likely to maintain flexibility
Markets will closely watch the press conference. Questions on French economic developments, sovereign spreads and ECB policy tools are expected, though Lagarde is unlikely to offer specific commentary at this stage.
Recent market moves have not been disorderly or irrational, and there is little evidence of widespread financial stress or fragmentation. Statements are expected to remain general. Lagarde may note that the Governing Council is monitoring financial conditions closely, while avoiding concrete references to spread levels or intervention triggers. Comments emphasising that primary responsibility lies with national fiscal authorities rather than the central bank are likely.
On monetary policy, Lagarde has already recognised that higher long-term rates will dampen growth and weaken transmission more than previously anticipated. She is expected to reiterate that the substantial tightening in financial conditions since September forms part of the Governing Council’s assessment of the appropriate policy stance. Policy optionality will remain a priority. Market pricing for a December hike stands at around 20 basis points.
Lagarde may also face questions surrounding speculation over her tenure. Without new concrete updates, her remarks are expected to stress policy continuity and collective Governing Council decision-making. Uncertainty over leadership complicates the ECB’s task amid tighter financial conditions, elevated energy costs and broader macroeconomic uncertainty.
EUR/USD remains confined within its range in the near term
The ECB’s hold decision was largely priced in and is unlikely to deliver an immediate impact on the euro. The direction of EUR/USD will hinge on shifts in signals from this meeting relative to the Federal Reserve’s policy path.
EUR/USD trades near 1.1150, close to the Oct 14 low. The Fed’s policy rate range of 3.75%-4.00% leaves a spread of 125 to 150 basis points over the ECB deposit rate. This differential has driven the euro’s range-bound performance since mid-September.
Should Lagarde frame tighter financial conditions as a substitute for policy action, markets may further scale back pricing for a December hike, removing a key support for the euro. If she keeps comments general and retains the option of action in December, downside pressure on the single currency will be limited.
Market pricing for a Fed rate hike in December has climbed to roughly 81%. If both central banks deliver a 25-basis-point increase, the interest rate spread would stay unchanged, leaving EUR/USD without a clear directional catalyst.
More Coverage


2026 © - All Rights Reserved by BCR Co Pty Ltd
Risk Disclosure:Derivatives are traded over-the-counter on margin, which means they carry a high level of risk and there is a possibility you could lose all of your investment. These products are not suitable for all investors. Please ensure you fully understand the risks and carefully consider your financial situation and trading experience before trading. Seek independent financial advice if necessary before opening an account with BCR.
Jurisdiction Notice:Our services are not intended for residents of the United States & Canada, and we do not intend to distribute or use the provided information in any country or jurisdiction where it would be contrary to local law or regulation. It is important that you read and consider the relevant legal documents associated with your account, including the Terms and Conditions issued by BCR before you start trading. BCR Co Pty Ltd is regulated by the British Virgin Islands Financial Services Commission, Certificate No. SIBA/L/19/1122. The Registration Number in the BVI is 1975046. The Registered Address of the Company is Trident Chambers, Wickham’s Cay 1, Road Town, Tortola, British Virgin Islands.
BCR Co Pty Ltd (Company No. 1975046) is a company incorporated under the laws of the British Virgin Islands, with its registered office at Trident Chambers, Wickham’s Cay 1, Road Town, Tortola, British Virgin Islands, and is licensed and regulated by the British Virgin Islands Financial Services Commission under License No. SIBA/L/19/1122.
Open Bridge Limited (Company No. 16701394) is a company incorporated under the Companies Act 2006 and registered in England and Wales, with its registered address at Kemp House, 160 City Road, London, England, EC1V 2NX. Open Bridge Limited acts solely as a payment processor for BCR Co Pty Ltd and does not provide any financial, trading, or investment services on its behalf. Open Bridge Limited's role is limited to payment processing.

 English
 简体中文
 繁體中文
 Bahasa
Melayu
 Tiếng
Việt
 ไทย
 日本語
 한국어
 ភាសាខ្មែរ
 español